Table of Contents
- Why Workers Comp Costs Keep Climbing for Construction Firms
- Step 1: Build a Formal Safety Program That Lowers Your Loss Ratio
- Step 2: How to Lower EMR Rating for Construction with Sustained Effort
- Step 3: Create a Workers Compensation Return to Work Policy Template
- Step 4: Tighten Payroll Reporting and Classification Codes
- Step 5: Manage Claims and Subcontractor Compliance Proactively
- How PEO Services for Construction Risk Management Fit In
- Conclusion
- Frequently Asked Questions
Last Updated: September 28, 2026
Why Workers Comp Costs Keep Climbing for Construction Firms
Workers comp costs for construction remain one of the hardest line items to control, even as the broader insurance market holds steady. According to Miller Cares’ 2026 market outlook, workers’ compensation rates are expected to stay stable into 2026. That sounds like good news until you look at what’s happening at the state level.
California approved a 10.4% workers’ compensation rate hike effective September 1, 2026. Other states are watching closely. For a contractor running crews across multiple job sites, a rate increase like that lands directly on the bottom line.
Here’s the part most owners miss: rates are only half the story. Your own claims history, payroll classification, and safety record drive the other half. That’s where NetPEO comes in. This guide breaks down five steps that actually move the needle on workers comp costs.
Most articles on this topic stop at “be safer.” That’s not a strategy. Below, we’ll show you exactly how to cut costs through safety programs, EMR management, return-to-work policies, payroll accuracy, and claims control.
Step 1: Build a Formal Safety Program That Lowers Your Loss Ratio
A formal safety program is the foundation of every cost-reduction effort. Without one, everything else falls apart.
The Construction Institute’s 2026 cost study identified 13 specific courses of action that reduce workers’ compensation claim costs. A written safety program sits at the top of that list.
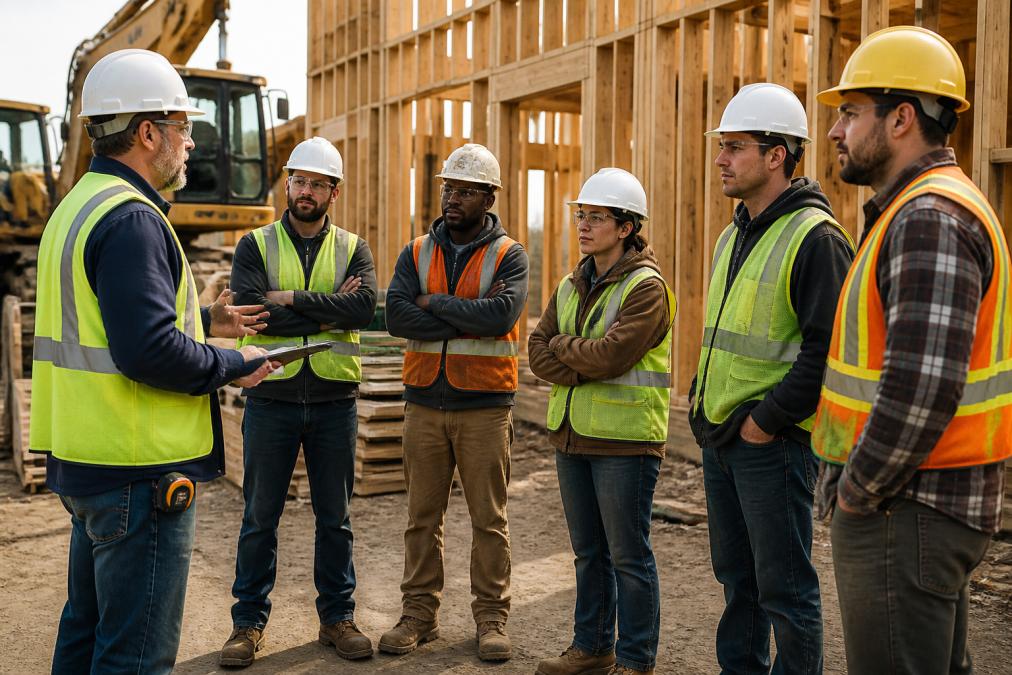
Consistent adherence to these protocols not only minimizes the frequency of insurance claims but also serves as the primary defense for avoiding workplace safety fines in an increasingly regulated environment.
Hazard Identification and Safety Training That Actually Sticks
Most safety training fails because it’s a video and a sign-in sheet. Workers nod along, then go back to the same habits.
What works instead:
- Daily toolbox talks focused on that day’s specific hazards
- Job hazard analyses for every task before work starts
- Hands-on training with the actual equipment crews use
- Near-miss reporting that doesn’t punish the reporter
The goal is a safety culture, not a safety binder. Companies that track near-misses catch problems before they become claims.
Technology-Driven Safety Monitoring on the Job Site
Wearable sensors, drone site scans, and AI camera systems now flag unsafe behavior in real time. This is one of the biggest gaps in competitor advice.
A sensor that buzzes when a worker enters an exclusion zone prevents the injury that would have spiked your loss ratio.
Step 2: How to Lower EMR Rating for Construction with Sustained Effort
Learning how to lower EMR rating for construction starts with understanding what the Experience Modification Rate actually is and how it is calculated. Your EMR compares your claims history to other contractors in the same classification. A 1.0 is average. Below 1.0 saves you money. Above 1.0 costs you.
How the Mod Is Actually Calculated (and Why It Matters)
Most contractors treat the EMR as a black box. It isn’t. The rating bureau that computes your mod, NCCI in most states, or a state bureau in monopolistic states, uses a formula built on three inputs:
- Expected losses for your classification and payroll (the “expected loss rate” multiplied by your exposure)
- Actual losses from your claims, split into “primary” losses (capped per claim) and “excess” losses (above the cap, weighted less heavily)
- Weighting factors that credit you for having predictable, low-severity claims versus one catastrophic claim
A Concrete Example of How One Claim Moves Your Premium
Say your manual premium before mod is $100,000 and your current EMR is 1.00, so you pay $100,000. A single lost-time claim with a reserve that pushes your mod to 1.15 means you now pay $115,000, a $15,000 increase. That higher mod follows you for three policy years, so the same claim can cost you roughly $45,000 in additional premium before it drops off, plus the indirect costs (overtime, retraining, schedule disruption) that typically run several times the direct claim.
Audit Your Mod Worksheet and Challenge Errors
Your mod worksheet is built from payroll and claims data your carrier reports to the bureau. Errors happen. A misclassified employee or a claim that should have been closed can inflate your rate.
Pull your worksheet every year. Check:
- Payroll totals against your actual records
- Claim reserves that never got adjusted after the worker recovered
- Classification codes that don’t match the work performed
- Claims that belong to a prior owner or a predecessor entity
Lowering your EMR is a three-year game. Every claim you prevent this year is still affecting your premium in year three. Treat the mod as a rolling liability, not an annual number.
Step 3: Create a Workers Compensation Return to Work Policy Template
A workers compensation return to work policy template is a written plan that brings injured employees back to modified duty as soon as a doctor clears them. It’s one of the fastest ways to cut claim costs.
Your template should include:
- Light-duty job descriptions ready before an injury happens
- A doctor communication form that specifies available restrictions
- A transitional duty schedule with clear start and end dates
- A signed acknowledgment from the employee
Transitional Duty Assignments That Reduce Claim Duration
Transitional duty means real work, not busy work. A carpenter with a shoulder injury can run inventory, do site cleanup, or handle tool maintenance. The point is to keep the worker connected and productive.
Step 4: Tighten Payroll Reporting and Classification Codes
Payroll errors and wrong classification codes are silent budget killers. They don’t show up until your premium audit, and by then you owe the difference plus penalties.
Key moves:
- Document per diem reimbursements separately from wages
- Reclassify workers when their job duties change
- Review 941s and certified payroll reports against your workers’ comp reports quarterly
Step 5: Manage Claims and Subcontractor Compliance Proactively
Claims management starts the day of the injury, not the day the claim hits your desk. Report every incident within 24 hours. Investigate immediately. Document everything.
Certificate of Insurance Verification: The Workflow That Actually Protects You
A certificate of insurance (COI) is not proof of coverage, it’s evidence of coverage on the date it was issued. Treat it that way.
A defensible COI workflow has five steps:
- Collect before mobilization. No COI, no site access. Make this a contractual condition, not a courtesy.
- Verify limits against your contract. Require general liability limits that match your subcontract, plus workers’ comp coverage at the statutory limit for the state where the work happens.
- Confirm additional insured status. Your sub’s GL policy should name you as an additional insured, and the endorsement should be attached, not just promised on the certificate.
- Require a waiver of subrogation on both the GL and workers’ comp policies. Without it, the sub’s carrier can pay the claim and then come after you.
- Track expiration dates monthly. A COI that was valid at signing is worthless if it lapsed three months into the job.
A certificate that lists your company as additional insured is not the same as an endorsement that actually grants it. Ask for the endorsement form. Carriers issue certificates with boilerplate language all the time.
How PEO Services for Construction Risk Management Fit In
PEO services for construction risk management give small and mid-sized contractors access to safety specialists, claims managers, and workers’ comp expertise they couldn’t afford to hire in-house.
| Your Challenge | What a PEO Handles | Impact |
|---|---|---|
| High EMR, no safety program | Safety audits and training | Lower mod rate over time |
| Payroll misclassification | Class code review | Fewer audit penalties |
| Claims dragging on | Return-to-work coordination | Shorter claim duration |
| Sub COI tracking | Compliance monitoring | Less liability exposure |
Conclusion
Construction workers’ comp costs won’t drop on their own. Stable market rates help, but your EMR, safety culture, and claims handling decide what you actually pay. The five steps above work together. Skip one, and the others lose power.
Frequently Asked Questions
What is the most effective way to lower workers’ compensation premiums in construction?
The most effective approach combines a formal safety program, accurate payroll classification, and a return-to-work policy. Loss prevention representatives help reduce injury rates and lower the cost of existing claims once they occur, according to ScienceDirect research. Preventing repeat injuries, auditing mod worksheets, and managing claims correctly are cited as key levers for 2026. No single tactic works alone; sustained effort across safety culture and claims management drives the biggest premium reductions over time.
How does an Experience Modification Rate impact construction insurance costs?
The Experience Modification Rate (EMR) is a critical factor that can significantly increase or decrease workers’ compensation insurance costs, according to OCMI Workers Comp. A mod rate above 1.0 raises your premium, while below 1.0 lowers it. Lowering the mod rate is a long-term process requiring sustained safety and hazard identification rather than a quick administrative change, per InvoPEO. Auditing your mod worksheet for errors is a practical first step.
How does return-to-work programming influence insurance premium calculations?
Return-to-work programs are cited as a primary strategy for reducing the financial impact of injuries, according to Insureon. When injured workers return to transitional duty faster, claim duration and lost wage costs drop, which improves your loss ratio and experience rating over time. A written policy that defines light-duty tasks and timelines gives claims adjusters clear options and reduces the chance of prolonged off-work claims that drive premiums up.
Can PEO services for construction risk management really reduce liability?
PEO services for construction risk management can help by consolidating safety training, claims management, and compliance tracking under one provider. The Construction Institute identified 13 specific courses of action recommended to reduce workers’ compensation claim costs, many of which align with PEO service offerings. Proactive management of payroll and classification codes is also identified as a key cost-reduction lever by Alliant. Results depend on your claims history and safety culture, so ask providers for specific risk management deliverables.